Top national TV ad spenders are difficult to rank across history because the public sources measure different things. Kantar’s annual advertiser lists cover total U.S. advertising across media, iSpot estimates national TV spend, category reports isolate specific windows, and Super Bowl prices describe a single event. This guide keeps those numbers separate instead of treating them as one audited leaderboard.
Historic all-media rankings still show which companies had the scale to support heavy television, while current TV datasets show where national spend is concentrating now. From a planning standpoint, the useful question is not who spent the most in absolute terms, but how reach, timing, brand strategy, and measurement worked together. Kantar’s 2018 ranking provides the historical advertiser context (Marketing Dive), while Amazon’s 2019 jump shows how quickly that context can change (Axios).
At a glance
- Historical advertiser scale: Kantar ranked P&G as the largest U.S. advertiser in 2018 at $2.9 billion across measured media. That is an all-media figure, not a TV-only total (Marketing Dive).
- Amazon’s jump: Amazon became the largest U.S. advertiser in 2019 at nearly $7 billion in total advertising. The figure should not be read as $7 billion of television spend (Axios).
- National TV now: iSpot publishes estimated national TV spend based on impressions and CPM assumptions, so its weekly leaderboard is a TV-specific snapshot rather than an audited company-wide advertising total (iSpot).
- Event economics: Super Bowl LIX in 2025 averaged a record 127.7 million viewers on the single-network telecast, with 30-second units reported as high as $8 million (Reuters). Super Bowl LX in 2026 averaged nearly 125 million viewers, while some 30-second units reached $10 million (Reuters 2026).
1) Procter & Gamble: the historic scale benchmark
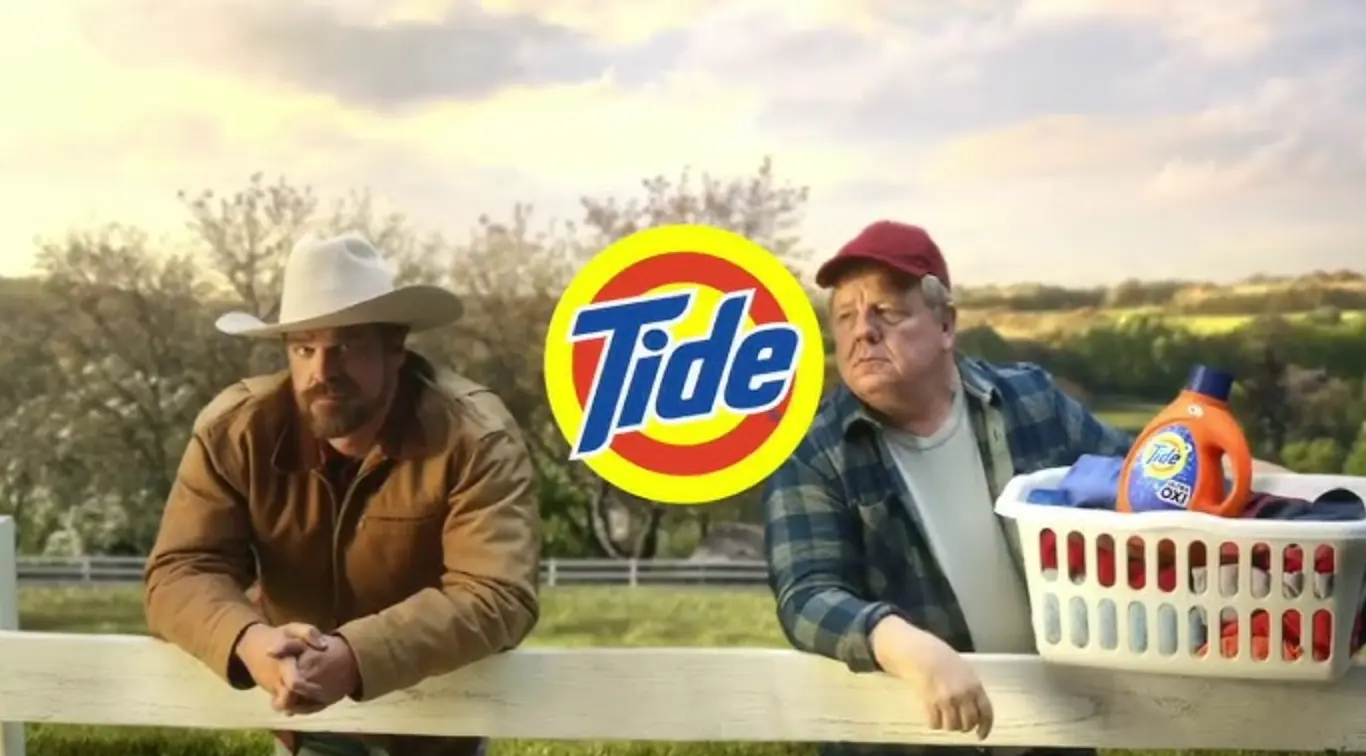
Procter & Gamble is a useful starting point because it has spent at enormous scale for decades across consumer categories built on broad reach and repeated brand memory. Kantar put P&G at $2.9 billion in U.S. advertising in 2018, but that number covers measured media broadly and should not be presented as national TV spend. Its television importance is better understood through the company’s long history of mass-reach creative and the continuing visibility of brands such as Tide, Febreze, and Pampers on national schedules (Marketing Dive, Wired).
- Use P&G’s $2.9 billion figure as evidence of advertiser scale, not as a TV-only total.
- Its longevity shows why television has historically fit brands that need broad awareness and repeated creative assets.
2) Amazon: a digital-first advertiser reaches mass scale
Amazon’s 2019 surge is another case where the denominator matters. Axios reported nearly $7 billion in U.S. advertising and the No. 1 advertiser position for the year, but that was total advertising, not a disclosed national TV budget. Prime, devices, retail promotions, and entertainment made mass reach strategically useful as Amazon moved deeper into mainstream households. The lesson for B2C marketing is that television can complement digital distribution when a consumer proposition needs rapid national awareness; for technology marketing, it also shows how a digital-native company can use traditional reach without abandoning digital acquisition (Axios, The Guardian).
- Amazon’s nearly $7 billion figure describes total U.S. advertising in 2019, not TV alone.
- The strategic takeaway is channel expansion at scale, not proof that television replaced digital media.
3) Telecom and media: large advertisers with built-in reach needs
Telecom and media companies regularly appear near the top of large-advertiser lists because they sell national connectivity, programming, subscriptions, and bundles. In Kantar’s 2018 all-media ranking, AT&T, Comcast, and other major corporate advertisers were among the country’s largest spenders (Marketing Dive). That does not establish a TV-only ranking, but it explains why these businesses have the scale and product cadence to remain visible on national television. For organizations coordinating national reach with a US marketing agency, the practical lesson is to treat TV as one part of a broader media system rather than using total corporate ad spend as a proxy for TV investment.
- All-media corporate rankings provide scale context, not channel-specific totals.
- Telecom and media brands have recurring reasons to advertise nationally: plans, launches, streaming, sports rights, and bundles.
4) Insurance: one of national TV’s most persistent categories
Insurance remains a particularly clear national TV category because the largest carriers compete for broad awareness in a market where many customers shop only at specific moments. iSpot’s weekly leaderboard regularly surfaces insurance advertisers (iSpot). Looking at a completed period rather than a single week, iSpot reported that insurance led linear-TV industry share of voice in the first half of 2026 and accounted for more than $1.32 billion in estimated national TV spend; Progressive ranked first among linear advertisers by share of voice (iSpot H1 2026).
That persistence does not mean every insurance brand should copy the same frequency. TV should sit inside a broader paid media plan that distinguishes reach, response, and incremental business outcomes.
- Insurance is a documented high-spend national TV category in current iSpot estimates.
- Frequency is useful only when creative recognition and measurement justify the repeated exposure.
5) Household products and healthcare: keep the categories separate
The pandemic-era evidence in this article covers two different advertiser groups. Household CPG brands such as Tide, Downy, and Febreze were visible national TV buyers in 2021; Adweek reported substantial spending for those P&G brands during the period (Adweek). They should not be labeled as pharma or healthcare advertisers.
Separately, the Center for Media Engagement studied advertising on nightly network and primetime cable news from January 2020 through June 2021. It found healthcare advertisers spent $307 million across that news inventory. The study’s $132 million figure refers to the top five healthcare advertisers per network across six networks, not total healthcare advertising. It is also a news-programming study, not a measure of all national TV (PDF). For health and wellness marketing, the broader lesson is to keep the category, period, and inventory definition attached to every spending claim.
- Household CPG and healthcare are separate categories and should not be combined in one spend total.
- The $307 million healthcare figure covers specific news inventory over an 18-month pandemic window.
6) Automotive: a large category with visible cycles
Automotive remains an important national TV category, but its spending moves with inventory, launches, incentives, and macro conditions. An earlier MediaPost report documented a sharp April 2025 decline in national TV activity (MediaPost). A year later, MediaPost reported $131.9 million in April 2026 national linear TV spend, down 18% from the prior April, reinforcing the point that even large traditional categories can contract materially from one period to the next (MediaPost 2026). Weekly rankings can then shift toward other categories as available inventory and campaigns change (iSpot).
- Automotive is strategically important to national TV, but its spend should be read by period rather than treated as constant.
- Year-over-year category changes can be large enough to reshape weekly advertiser rankings.
7) Retail and ecommerce: event-driven national reach
Retailers often increase mass-reach advertising around periods when demand is already elevated, including back-to-school, Black Friday, and the holiday season. Amazon’s 2019 all-media surge is useful context for how a retail platform can dramatically increase total advertising when Prime, devices, and entertainment all need support, but it should not be converted into a TV-only number (Axios). National TV can still be valuable in those windows when the goal is to make a promotion or brand message visible at scale.
- Retail TV budgets are often tied to calendar moments, launches, and promotions rather than a flat year-round level.
- Judge the channel by incremental reach and business response, not by the size of another retailer’s total advertising budget.
View this post on Instagram
A post shared by Target (@target)
8) Entertainment and streaming: television markets television
Streamers, studios, and media owners use national TV to promote shows, live sports, movies, bundles, and subscriptions. That can make media companies visible both as sellers of advertising inventory and as advertisers for their own content. Historical all-media rankings provide corporate scale context (Marketing Dive), while iSpot’s TV-specific leaderboard shows which campaigns are active in a given week (iSpot). In entertainment marketing, the useful distinction is between corporate advertising totals and the national TV spend attached to a particular release, service, or rights package.
- Media companies can appear on both sides of the TV advertising market.
- Release calendars and sports rights can create concentrated national-TV bursts rather than constant spend.
9) Sports: where national TV prices concentrate
Live sports remain one of television’s clearest high-attention environments. Super Bowl LIX in 2025 set the U.S. single-network audience record at 127.7 million viewers (Reuters). Super Bowl LX in 2026 averaged nearly 125 million viewers and some 30-second units reached $10 million, illustrating how event pricing can climb even when the audience is slightly below the prior year’s record (Reuters 2026). Out-of-home viewing can also add audience beyond the living room, which is why sports measurement needs to account for where viewing occurs (Nielsen).
Those prices belong to a premium event market, not to ordinary national TV. For examples of how airtime and production costs differ, see the most expensive commercials; for campaign strategy around leagues, athletes, and events, see the sports marketing campaigns guide.
- Super Bowl pricing is an event benchmark, not a general national-TV rate.
- Audience scale, scarcity, and cultural attention all contribute to the premium.
FAQ
Is there a definitive all-time ranking of national TV ad spenders?
No single public, audited ledger covers every advertiser and every year on a consistent TV-only basis. Historic all-media rankings are useful context, while iSpot and category reports provide TV-specific estimates for defined periods.
Was P&G’s $2.9 billion in 2018 all national TV?
No. The Kantar figure cited here was total U.S. measured advertising across media. P&G’s television presence is important, but the $2.9 billion number should not be labeled a TV-only budget.
Was Amazon’s nearly $7 billion in 2019 all television?
No. Axios reported nearly $7 billion in total U.S. advertising. It demonstrates advertiser scale, not a disclosed national TV total.
Why does insurance appear so often in national TV rankings?
Insurance brands compete in a broad consumer market where ongoing awareness matters. iSpot’s first-half 2026 data placed insurance first among industries by linear-TV share of voice and reported more than $1.32 billion in estimated national TV spend.
Did healthcare advertisers spend $132 million on all TV during the pandemic?
No. The cited study found $307 million in healthcare advertising on nightly network and primetime cable news from January 2020 through June 2021. The $132 million figure covered the top five healthcare advertisers per network across the six networks studied.
What does the Super Bowl tell us about national TV spending?
It shows how scarcity and audience concentration can create exceptional event pricing. In 2026, some 30-second units reached $10 million, but that should not be treated as a standard national-TV benchmark.
Why do retail advertisers become more visible around Q4?
Holiday demand, promotions, product launches, and sports programming can make broad reach more valuable. The right comparison is incremental reach and business response, not another company’s total media budget.
Where TV Spend Meets Strategy
The biggest lesson from national TV spending is methodological: compare like with like. All-media advertiser totals, estimated national-TV spend, category snapshots, and event pricing answer different questions. Brand Vision approaches channel planning from that distinction, because media scale only creates value when the audience, message, and measurement framework are aligned.
For businesses deciding whether television belongs in a broader growth plan, a branding agency can help clarify the message before reach is purchased, while an integrated marketing agency can connect TV with the rest of the channel mix and measurement.