SEO is paying off when the additional business it generates contributes more than the work costs. To measure SEO return on investment (ROI), connect organic visits to sales or qualified leads, account for the costs of serving those customers, and compare the remaining contribution with the full SEO investment.
That sounds straightforward until the reporting arrives. Clicks may be growing on pages that rarely attract buyers. Leads may take months to close. Analytics may credit organic search for customers who already intended to buy.
A useful SEO ROI assessment works through those uncertainties. Historical lead data can support an estimate before every deal closes, while actual sales provide a later check.
Start by defining what you are evaluating: the existing organic channel, a specific SEO initiative, or additional spending. Revenue associated with established pages does not, by itself, show what the latest retainer or project produced.
Check whether organic growth is reaching potential customers
A large increase in impressions or clicks deserves investigation before it becomes a success claim.
Look at which queries and pages account for the change. Are people searching for something the business sells? Are they reaching pages that help them evaluate the offering? Does that traffic progress into relevant enquiries, qualified opportunities, or purchases?
Consider a service business whose growth comes mainly from general informational articles. Those articles might attract a substantial audience, while enquiries for its services remain unchanged. A smaller increase on pages addressing a specific buying decision could have greater immediate commercial value.
That does not make informational content worthless. It may help people understand a problem or evaluate a future purchase. The question is whether its contribution matches the purpose assigned to it, and whether there is evidence of progress beyond the visit.
Group performance by meaningful query themes and landing pages, then connect those groups to lead quality and customer outcomes. A site-wide traffic total can hide differences between services, audiences, and types of content.
Google Search Console helps with the search side of that investigation, but its query data is incomplete. Google documents that some queries are omitted for privacy and others may be truncated. A query export therefore cannot support a complete, precise keyword-to-revenue calculation.
Use Search Console to understand search visibility and query patterns. Use analytics and customer records to examine what happens after visits. Keep each report’s definitions intact rather than combining incompatible totals into a seemingly precise conversion rate.
A system of SEO reporting tied to leads gives the financial calculation a useful foundation: relevant demand, identifiable landing pages, and commercial progression.
Measure sales or estimate the value of qualified leads
The appropriate method depends on how customers buy. An online purchase and a sales enquiry represent different stages, even when both appear as valuable actions in an analytics dashboard.
When purchases happen online
Start with purchase records and a consistent definition of net sales. Decide whether the assessment covers first purchases or a defined period of subsequent customer revenue.
In GA4, purchase revenue subtracts recorded refunds. Reconcile the analytics figure with order or financial records so that missing refunds, incomplete tracking, or duplicate transactions do not distort the assessment. Financial records establish the sales amount; the analytics configuration supplies the chosen view of channel credit.
Then account for the variable costs associated with those sales. A business that receives $30,000 in revenue has not necessarily gained $30,000 it can use to recover its SEO investment.
Keep received cash separate from recorded revenue when payment timing matters. A profitable order and a paid invoice answer different questions about the business.
When leads close later
You do not have to wait for every current lead to close before making a provisional assessment.
Historical results can help estimate the value of qualified leads. The basic calculation is:
Expected contribution = Qualified leads × Expected close rate × Expected contribution per customer
Each input needs a clear definition. If the close rate applies to sales-qualified opportunities, the lead count must use that same qualification stage. Applying an opportunity close rate to every contact-form submission would inflate the estimate.
Use historical groups of comparable leads that have had enough time to progress through the sales process. Record how still-open opportunities are treated. Do not quietly remove unresolved leads from the denominator to make the closing rate look stronger.
Comparability matters as much as the amount of history. A new service, different customer segment, or changed qualification process may make the old rate less useful. Where evidence is limited, calculate a reasonable range rather than presenting one precise forecast.
Assigning a monetary value to a lead inside an analytics tool does not make it sales revenue. Google’s metric definitions distinguish event value, which can include unrealized values, from purchase revenue.
As deals resolve, record won and lost outcomes while keeping any remaining forecast for open leads separate. Once the group has matured, compare its actual results with the original estimate. Do not count both a lead’s estimated value and the eventual sale as separate returns.
How to calculate SEO ROI with full costs
Once the outcome measure is defined, build the cost side with equal care. An accurate revenue estimate paired with an incomplete investment figure still produces a misleading result.
Count external fees and internal work
SEO investment can include agency or consultant fees, content production, development, software, and measurement. It can also include employees’ time spent briefing, reviewing, implementing, and maintaining the work.
Separate costs paid directly to suppliers from internal resources assigned to the programme. Both can matter to the decision, even when internal time does not create an additional invoice.
Shared work needs a consistent allocation. A website improvement may support organic search, paid campaigns, and existing customers. Document the portion assigned to the SEO assessment instead of charging the entire project to whichever channel is being reviewed.
Check what an SEO budget includes, particularly the responsibilities that remain with the business after an external fee is agreed.
Match costs to the scope of the return. A project assessment should include the relevant research, production, implementation, and ongoing expenses. Comparing several years of expected customer value with one month of SEO spending would need a much more explicit model.
Compare contribution with cost
Contribution is the sales revenue remaining after variable costs. Expressed as a percentage of sales, it is the contribution margin ratio. That remainder helps cover fixed costs and profit, as explained in OpenStax’s contribution margin guidance.
For an SEO investment review, calculate contribution before subtracting the SEO costs you have assigned to the programme. Otherwise, those costs could be deducted twice.
A practical calculation is:
Contribution-based return = (Contribution credited to organic search − SEO investment) ÷ SEO investment × 100
The label should reflect the evidence. Use expected contribution for a forecast and attributed contribution when the amount depends on channel credit. Neither automatically establishes an incremental return.
Consider a hypothetical programme with these assumptions:
- 50 qualified leads credited to organic search.
- A 20% expected close rate, informed by comparable historical leads.
- $3,000 in net revenue per customer from the initial contract.
- A 40% contribution margin ratio before SEO costs.
- $10,000 in SEO costs assigned to the programme being evaluated.
The model predicts 10 customers and $30,000 in revenue. At that margin, this provides $12,000 before SEO costs.
Subtracting the $10,000 investment leaves $2,000, producing a 20% expected contribution-based return.
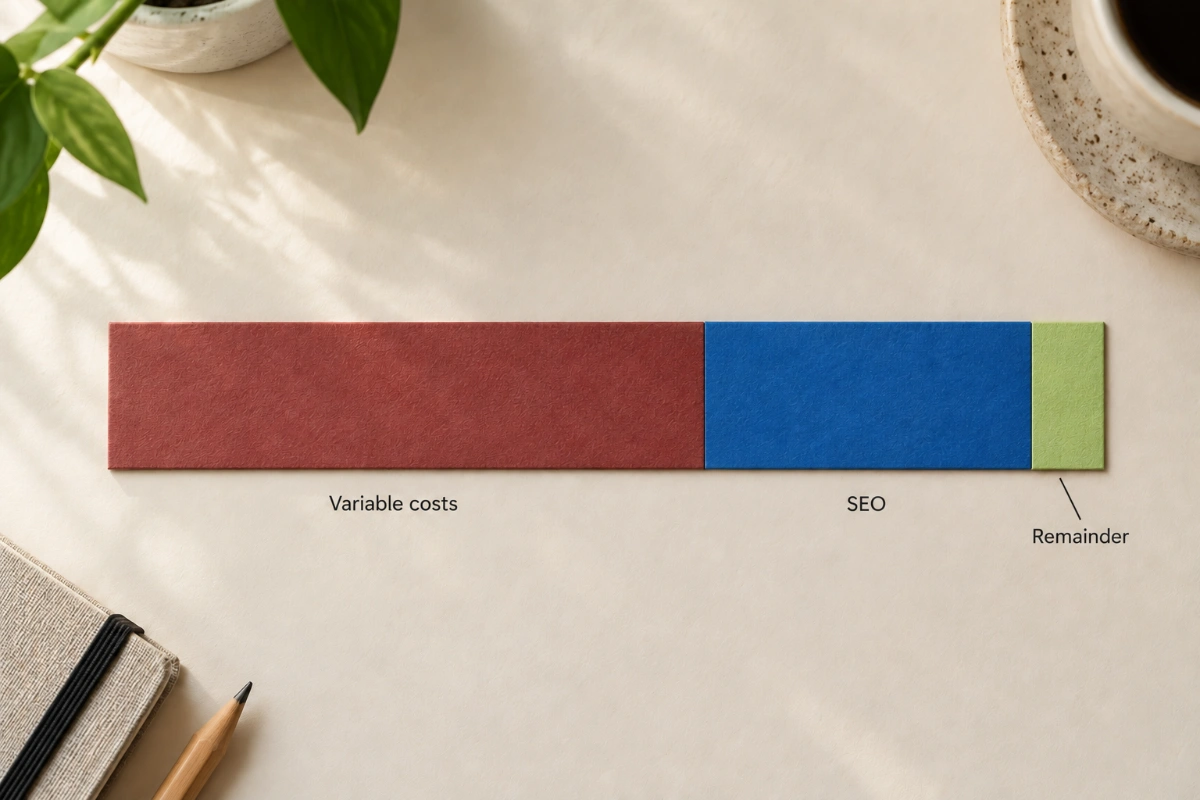
A calculation using revenue minus SEO cost would instead report 200%. It would overlook the variable costs required to deliver those sales. The contribution-based figure is more useful for this decision, although it still does not represent company-wide net profit after all overhead and taxes.
Now reduce the assumed close rate to 10%. Expected revenue falls to $15,000 and contribution to $6,000. Against the same investment, the expected return becomes −40%.
That sensitivity identifies what needs scrutiny: whether the current leads can reasonably perform like the historical group.
At the assumed margin, recovering $10,000 requires $25,000 in incremental revenue. This applies the logic of break-even analysis to the programme. It establishes the revenue requirement, not proof that SEO will generate it.
Separate attributed value from incremental results
Attribution asks which channel receives credit for an outcome. Incrementality asks how much additional business occurred because of the investment.
A prospect might discover a company through a referral, search its name, and submit an enquiry. Organic search played a role in that journey. Whether the current SEO work created an additional customer is a separate question.
Even attributed figures require consistent reporting choices. Google explains that changing GA4’s reporting attribution model affects event-scoped traffic dimensions, while user- and session-scoped dimensions are unaffected by that setting. Two reports can therefore answer different questions despite both appearing to show organic performance.
Record the report, channel definition, attribution model, and time period used. Avoid switching between views simply because one produces a more favourable result.
Brand and non-brand segmentation can help investigate the source of growth, but neither segment proves who created the demand. Search Console also acknowledges that its branded-query classification can be incorrect.
Assess other changes that could explain the outcome. Promotions, seasonality, pricing, sales activity, and website changes may all need consideration. A simple comparison with the previous month does not isolate the effect of SEO.
Where the decision warrants deeper analysis, a controlled comparison or carefully designed model may help estimate what would have happened without the intervention. Research on causal impact estimation makes the importance of suitable comparisons and assumptions explicit. Such methods require more than placing a trend line before and after a launch.
When that evidence is unavailable, keep the attributed estimate and its limitations visible. Do not invent an incremental percentage to complete the spreadsheet.
Match the review period to implementation and sales timing
An SEO programme has several relevant dates: when work was commissioned, when changes went live, when leads arrived, when deals closed, and when payment was received.
Those dates should inform the review.
If a service page launched recently and the business has a lengthy sales process, a lack of closed revenue may say little about that page’s eventual contribution. Qualified leads and a historical value model can support an interim decision.
However, a forecast should not remain permanently insulated from actual results. Group leads by when they entered the pipeline and revisit each group as it matures. If closing rates or deal values repeatedly fall short, revise the assumptions.
Keep a cumulative view of programme costs and outcomes alongside the current reporting period. A strong month does not necessarily recover earlier investment, while a weak month does not necessarily invalidate a profitable programme.
GA4’s attribution lookback window governs which earlier touchpoints are eligible for credit. It is not a substitute for following a long sales cycle through customer records.
Set the next reassessment point using implementation progress and the business’s observed sales timing. Specify what evidence should be available then, such as a mature group of leads or enough completed orders to evaluate margin.
There is no useful universal deadline that makes every SEO investment successful or unsuccessful. The review needs enough time to observe the intended outcome, while preserving a clear opportunity to change course.
Decide whether to expand, change strategy, or reconsider the opportunity
The calculation should lead to a decision about the next investment.
If tracking is unreliable, establish which outcomes can be trusted and repair the missing measurement. If relevant leads are progressing but remain immature, continue against a defined reassessment point. Neither situation justifies treating the current ROI number as settled.
When the evidence is sufficiently mature, investigate the reason for the result.
Reassess demand and attainable acquisition
Before investing, examine whether potential customers use search to find the offering, whether enough commercially relevant demand exists, and whether the business has a plausible way to reach it at an acceptable cost.
Revisit those assumptions when returns remain weak.
Work backward from the economics. How much contribution must the programme produce? How many customers would that require? Given a defensible closing rate, how many qualified leads would be needed?
Then compare that requirement with the opportunity. A high-value niche can justify investment with relatively few customers. A lower-margin offering may need a level of acquisition the available demand cannot support. Search volume alone does not resolve that difference.
Competition should be assessed in the same context. Consider what it would take to compete, the resources available, and the value of the attainable business. A keyword-difficulty score is not a financial feasibility assessment.
Where the obstacle concerns search visibility or the relevance of the pages being found, an SEO audit can help investigate and prioritize the work.
If relevant visitors already arrive but fail to enquire or buy, investigate the offer and customer journey. It may be more useful to diagnose weak website conversion or examine sales follow-up than to commission more content.
Positive returns also need interpretation. The next tranche of spending may target a different audience, require more expensive work, or face weaker demand. Assess the next investment on its own assumptions rather than extending the historic return indefinitely.
Evaluate any goal to reduce advertising dependence
Building organic acquisition can be part of a plan to reduce dependence on ongoing advertising. Make that objective measurable without assuming that paid and organic traffic are interchangeable.
A lower advertising bill is not sufficient if qualified demand and contribution fall with it.
In a randomized experiment involving Edmunds’ branded searches on Bing and Yahoo in 2015, organic traffic did not fully replace the paid traffic lost when advertising was reduced. That historical, company-specific study is not a benchmark for a current SEO programme. It illustrates why substitution needs to be evaluated in context.
If advertising expenditure changes, examine the combined effect on customer acquisition, contribution, and total spending. Avoid presenting an estimated cost of buying equivalent clicks as money the business actually saved.
Also avoid double-counting. Savings already reflected in lower acquisition expenses should not be added again as a separate return, and a customer should not be counted twice because both channels touched the journey.
For the next budget review, bring together the qualified outcomes, expected and realized contribution, full investment, and assumptions most capable of changing the conclusion. Use that evidence to decide what to fund, what to investigate, and when to reassess. A useful SEO ROI report makes the next spending decision clearer.